LibraryRed Capitalism The Fragile Financial Foundation of China´s Extraordinary Rise
Contents
Preface
List of Abbreviations
Chapter 1 : Looking Back at the Policy of Reform and Opening
Thirty Years of Opening up: 1978–2008
Thirteen Years of Reform: 1992–2005
The End of Reform: 2005
China is a Family Business
Endnotes
Chapter 2 : China’ s Fortress Banking System
Banks are China’ s Financial System
Crisis: The Stimulus to Bank Reform, 1988 and 1998
China’ s Fortress Banking System in 2009
The Sudden thirst for Capital and Cash Dividends, 2010
Endnotes
Chapter 3 : The Fragile Fortress
The People’ s Bank of China Restructuring Model
The Ministry of Finance Restructuring Model
The “Perpetual Put” Option to the PBOC
China’ s Latest Banking Model
Implications
Endnotes
Chapter 4 : China’ s Captive Bond Market
Why does China have a Bond Market?
Risk Management
The Base of the Pyramid: “Protecting” Household Depositors
Endnotes
Chapter 5 : The Struggle over China’ s Bond Markets
The CDB, the MOF and the Big 4 Banks
Local Governments Unleashed
China Investment Corporation: Lynchpin of China’ s Financial System
Cycles in the Financial Markets
Endnotes
Chapter 6 : Western Finance, SOE Reform and China’ s Stock MarketsChina’ s Stock Markets Today
Why does China have Stock Markets?
What Stock Markets gave China
Endnotes
Chapter 7 : The National Team and China’ s Government
Zhu Rongji’ s Gift: Organizational Streamlining, 1998How the National Team, Its Families and Friends BenefitA Casino or a Success, or Both?
Implications
Endnotes
Chapter 8 : The Forbidden City
The Emperor of Finance
Behind the Vermillion Walls
An Empire Apart
Cracks in the Walls
Imperial Ornaments
Endnotes
Appen dix
Select Bibliography
Index
Copyright © 2011 John Wiley & Sons (Asia) Pte. Ltd.
Published in 2011 by John Wiley & Sons (Asia) Pte. Ltd.
2 Clementi Loop, # 02-01, Singapore129809
All rights reserved.
No part of this publication may be reproduced, stored in a retrieval system, or transmitted inany form or by any means, electronic, mechanical, photocopying, recording, scanning, orotherwise, except as expressly permitted by law, without either the prior written permission ofthe Publisher, or authorization through payment of the appropriate photocopy fee to theCopyright Clearance Center. Requests for permission should be addressed to the Publisher, JohnWiley & Sons (Asia) Pte. Ltd. , 2 Clementi Loop, # 02-01, Singapore 129809, tel: 65-6463-2400,fax: 65-6463-4605, e-mail: enquiry@wiley.com.
This publication is designed to provide accurate and authoritative information in regard to thesubject matter covered. It is sold with the understanding that the publisher is not engaged inrendering professional services. If professional advice or other expert assistance is required,the services of a competent professional person should be sought.
Neither the author nor the publisher are liable for any actions prompted or caused by theinformation presented in this book. Any views expressed here in are those of the author and donot represent the views of the organizations they work for.
Other Wiley Editorial Offices
John Wiley & Sons, 111 River Street, Hoboken, NJ07030, USA
John Wiley & Sons, The Atrium, Southern Gate, Chichester, West Sussex, P019 8SQ, United KingdomJohn Wiley & Sons (Canada) Ltd. , 5353 Dundas Street West, Suite 400, Toronto, Ontario, M9B 6HB,Canada
John Wiley & Sons Australia Ltd, 42 McDougall Street, Milton, Queensland 4064, AustraliaWiley-VCH, Boschstrasse 12, D-69469 Weinheim, Germany
Library of Congress Cataloging-in-Publication Data
ISBN 978-0-470-82586-0 (Hardcover)
ISBN 978-0-470-82894-6 (e-book)
ISBN 978-0-470-82893-9 (e-book)
ISBN 978-0-470-82895-3 (e-book)
To John Wilson Lewis
Preface
After three rounds of Privatizing China, our book about China’ s stock markets, we felt like wewanted to look into something new. Since we took our first look at the stock markets in 1999,we have been interested to note the lack of work on the financial side of China’ s miracle thatgets beyond the macroeconomics of things. We are the first to agree that living and working inthe country for 25 years may not qualify us as experts in economics. We do believe, however,that our experience has given us a feel for how China’ s political elite manages money and thecountry’ s economy. Having worked in banks for longer than we care to remember, we wanted totry to understand how China and its ruling class finance themselves and we knew we had to beginwith the banks since, in truth, they are China’ s financial system. Those looking for tales ofcorruption and princelings with their hands in the till will be disappointed though. We thinkthat the financial side of the story behind a 30-year boom that changed the lives of onebillion people is much more interesting; so this is our effort at staking out modern China’ spolitical economy “inside the system. ”
We do not believe in Chinese exceptionalism. China’ s economy is no different from any other,in spite of the inevitable Chinese characteristics. If there are such things as economic laws,they work just as well in China and for Chinese businesses as they do in other markets. We alsodo not believe in the recent triumphalism of China’ s bankers and many of its leaders; this isonly a diplomatic ploy. China’ s banks survived the global financial crisis, as one seniorbanker has publicly stated, simply because the financial system is closed off from the world.Having seriously studied the collapse of Mexico’ s peso in 1994, the Asian Financial Crisis of1997 and those sovereign-debt crises that have followed, China’ s political elite has nointention of exposing itself to international capital markets. The domestic economy and marketsare, and will continue to be, most deliberately closed off. With a non-convertible currency,minimal foreign participation and few overseas assets beyond US Treasuries and commodityinvestments that will neither be marked-to-market nor sold, why shouldn’ t the system survive amajor international crisis better than open economies? China’ s financial system is designed sothat no one is able to take a position opposite to that of the government.
Of course, the private export-oriented sector suffered massive losses in jobs, earnings and theclosure of small companies in 2008 and 2009. But China’ s banks were not exposed in anymaterial way to this sector. It is a simple fact that China’ s financial system and its stock,bond and loan markets cater only to the state sector, of which the “National Champions”represent the reddest of the Red. These corporations, the heart of China’ s state-ownedeconomy, are “inside the system. ” The private economy, no matter how vibrant, is “outsidethe system” and, in fact, serves at the will of the system. If nothing else, the events of thefall of 2008 added an additional seal to the Party’ s determination to sustain a closed,tightly controlled, economy. “Don’ t show me any failed models, ” is the refrain of theChinese officialdom these days. But is China’ s own financial system a model for the world tostudy? Can China be thought of as an economic superpower, either now or in the future, withsuch a system?
With this sort of question in mind, we began to look at the financial history of the People’ sRepublic of China. We were fortunate that 2008 was the thirtieth anniversary of China’ s highlysuccessful Reform and Opening Policy, so there were many excellent retrospectives prepared bythe government agencies. The People’ s Bank of China, in particular, produced very usefulmaterial, some of which took one of us back 30 years to Beijing University where his study ofChinese banks began. We hasten to emphasize that all the information used in writing this bookderives from purely public sources. In China, all of the important ministries, corporations andbanks maintain excellent websites, so data is just out there in the wind waiting to bedownloaded. In particular, China Bond and the National Association of Financial MarketInstitutional Investors (NAFMII) , a sub-set of the People’ s Bank, have extensive websitesproviding access to information, in both Chinese and English, on China’ s fixed-income markets.Data for the stock markets have always been plentiful and, we believe, accurate. Again, Wind
Information, China’ s Bloomberg equivalent, has been a rich source for us. Then, there are theaudited financial statements of China’ s banks, all available online since the respectivelistings of each bank. Reading these statements has been highly educational. We stronglyencourage others, including China’ s regulators, to do the same.
So the modern age of technology provided all the dots that, linked together, present a pictureof the financial sector. How they are connected in this book is purely the authors’ collectiveresponsibility: the picture presented, we believe, is accurate to the best of our professionaland personal experience. We hope that this book will, like Privatizing China, be seen as aconstructive outsiders’ view of how China’ s leadership over the years has put together whatwe believe to be a very fragile financial system.
For all the fragility of the current system, however, one of us is always reminded that hisjourney in China began in Beijing back in 1979 when the city looked a lot like Pyongyang. WithNorth Korea in the headlines again for all the wrong reasons, it is worth remembering andacknowledging the tremendous benefits the great majority of Chinese have reaped as a result ofthe changes over the past 30 years. This can never be forgotten, but it should also not be usedas an excuse to ignore or downplay the very real weaknesses lying at the heart of the financialsystem.
We would like to thank those who have helped us think about this big topic, including in noparticular order Kjeld Erik Brosdgaard, Peter Nolan, Josh Cheng, Jean Oi, Michael Harris,Arthur Kroeber, Andrew Zhang, Alan Ho, Andy Walder, Sarah Eaton, Elaine La Roche and VictorShih. Over the years we have grown to greatly appreciate our friends at John Wiley, startingwith Nick Wallwork, our publisher who kickstarted our writing career in 2003, Fiona Wong, JulesYap, Cynthia Mak and Camy Boey. Professionals all, they made working on this book easy andenjoyable. John Owen was an unbelievably quick copyeditor and Celine Tng, our proofreader, gave“detail-oriented” a whole new definition! We thank you all for your strong support. What wehave written here, however, remains our sole responsibility and reflects neither the views ofour friends and colleagues, nor those of the organizations we work for.
We have dedicated the book to John Wilson Lewis, Professor Emeritus of Political Science atStanford University. John was the catalyst for Carl’ s career in China and, indirectly,Fraser’ s as well. Without his support and encouragement, it is fair to say that this book andanything else we have done over the years in China might never have happened. We both continueto be very much in debt to our wives and families who have continued to at least tolerate ourcurious interest in Chinese financial matters. We promise to drop the topic for a while now,even though we are well aware that there remains much that needs to be looked at in thefinancial space, including trust companies and asset-transfer exchanges. May be next time.Beijing and Singapore
October 2010
List of Abbreviations
ABCAgricultural Bank of ChinaAMCasset-management companyBOCBank of ChinaCBRCChina BankingRegulatory CommissionCDBChina Development BankCGBChinese government bondCICChina InvestmentCorporationCPcommercial paperCSRCChina Securities Regulatory CommissionICBCIndustrial andCommercial Bank of ChinaMOFMinistry of FinanceMORMinistry of RailwaysMTNmedium-term notesNAVnet asset valueNDRCNational Development and Reform CommissionNPCNational People’ s CongressNPLnon-performing loanPBOCPeople’ s Bank of ChinaSAFEState Administration for Foreign ExchangeSASACState-owned Assets Supervision and Administration Commission
- LibraryRed Capitalism The Fragile Financial Foundation of China´s Extraordinary Rise相关文档
- 操作手册RED SCARLET-X 摄影机 V205 中文操作手册
- 产区Red wine knowledge 1txt
- Kotaro押尾的《Red Shoes Dance》吉他谱
- roseA Red ,Red Rose 赏析
- 飞行员The Red Baron《红男爵(2008)》完整中英文对照剧本
- 学生小学三年级英语:Unit6 lesson1 It’s red 教学设计
Cloudxtiny:£1.5/月,KVM-512MB/100GB/英国机房
Cloudxtiny是一家来自英国的主机商,提供VPS和独立服务器租用,在英国肯特自营数据中心,自己的硬件和网络(AS207059)。商家VPS主机基于KVM架构,开设在英国肯特机房,为了庆祝2021年欧洲杯决赛英格兰对意大利,商家为全场VPS主机提供50%的折扣直到7月31日,优惠后最低套餐每月1.5英镑起。我们对这场比赛有点偏见,但希望这是一场史诗般的决赛!下面列出几款主机套餐配置信息。CPU...
云俄罗斯VPSJusthost俄罗斯VPS云服务器justg:JustHost、RuVDS、JustG等俄罗斯vps主机
俄罗斯vps云服务器商家推荐!俄罗斯VPS,也叫毛子主机(毛子vps),因为俄罗斯离中国大陆比较近,所以俄罗斯VPS的延迟会比较低,国内用户也不少,例如新西伯利亚机房和莫斯科机房都是比较热门的俄罗斯机房。这里为大家整理推荐一些好用的俄罗斯VPS云服务器,这里主要推荐这三家:justhost、ruvds、justg等俄罗斯vps主机,方便大家对比购买适合自己的俄罗斯VPS。一、俄罗斯VPS介绍俄罗斯...
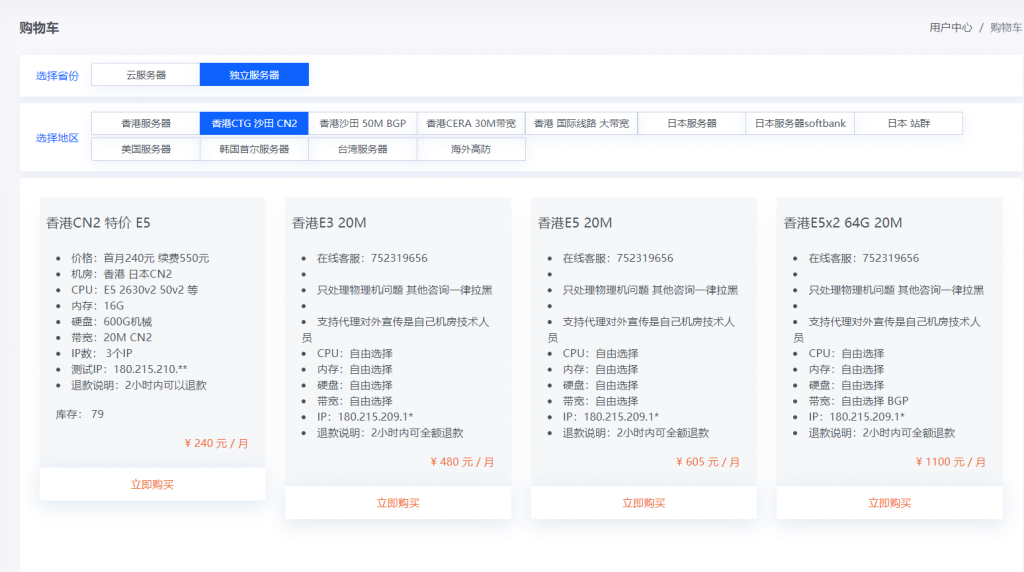
819云(240元)香港CN2 日本CN2 物理机 E5 16G 1T 20M 3IP
819云是我们的老熟人了,服务器一直都是稳定为主,老板人也很好,这次给大家带来了新活动,十分给力 香港CN2 日本CN2 物理机 E5 16G 1T 20M 3IP 240元0官方网站:https://www.819yun.com/ 特惠专员Q:442379204套餐介绍套餐CPU内存硬盘带宽IP价格香港CN2 (特价)E5 随机分配16G1T 机械20M3IP240元/月日本CN2 (...
-
郭吉军新媒体营销的咨询行业有哪些好的老师?暴风影音怎么截图暴风影音怎么截屏啊?万网核心代理在万网代理商购买万网产品,谁知道价格?知道的说下?伪静态什么是伪静态网站运营一般网站如何运营童之磊湖北中文在线数字出版有限公司怎么样?畅想中国未来的中国是什么样子的xp系统停止服务XP停止服务后该怎么办?qq空间打扮QQ空间打扮小米手柄小米手柄能连几个手机