promotefilemarkets.com
filemarkets.com 时间:2021-03-21 阅读:()
ENEN21.
INTRODUCTIONTaxationiscentraltotheEU'sworktobuildastronger,morecompetitiveandfairereconomy,withaclearsocialdimension.
Europeneedsataxsystemthatfitsitsinternalmarketandthatsupportseconomicgrowthandcompetitiveness,attractsinvestment,helpstocreatejobs,fostersinnovationandupholdstheEuropeansocialmodel.
Taxationshouldprovidestablerevenuesforpublicinvestmentandgrowth-friendlypolicies.
Itshouldensurethatallbusinessesenjoyalevel-playingfield,legalcertaintyandminimalobstacleswhenoperatingcross-border.
Itshouldbepartofawidertaxsysteminwhichcitizenshaveconfidence,becauseitisfairandmeetssociety'ssocio-economicneeds.
TheEU'sprioritiesintaxationarethereforefocussedonthesegoals.
2.
IMMEDIATEACTIONTOMEETIMMEDIATENEEDS:REFORMINGCORPORATETAXATIONTheCommissionhassetanambitiousagendatomakecorporatetaxationfairerandmoreeffective;betteradaptedtothemoderneconomyandmoreresponsivetoemergingchallengesinthisfield.
Thisagendaisadvancingrapidlyandmanyimportantmilestoneshavealreadybeenmet.
AlloftheinitiativesannouncedintheCommission'sActionPlanforFairandEffectiveTaxation1havenowbeenlaunched,andmanynewproposalshavealreadybeenadoptedbyMemberStates.
TheCommissionisalsopushingthescopeofitsworkbeyondtheActionPlan.
AsshownintheCommunicationonfurthermeasurestoenhancetransparencyandthefightagainsttaxevasionandavoidance,whichfollowedthePanamaPapersrevelations,itisreadytodevelopswiftandeffectiveresponsestoissuesastheyarise2.
Inaddition,theCommissionhascarriedoutstateaidinvestigationsintowhethercertainMemberStatesgrantedtaxadvantagestoselectedmultinationalcompanies3,tosafeguardafairandcompetitiveenvironmentforallbusinessesintheEU.
TheCommission'sfirstlineofactionwastoincreasetaxtransparency,asanessentialfoundationforanyfurtherreforms.
Withinaperiodof12months,MemberStatesagreedonproposalsfortheautomaticexchangeofinformationontaxrulings4andcountry-by-countryreportsoftax-relatedinformationconcerningmultinationals5.
Thiswillbringanewandunprecedentedleveloftransparencyandcooperationbetweentaxauthoritiesintheareaofcorporatetaxation.
TheCommissionalsoproposedpubliccountry-by-countryreportingformultinationals,toprovidecitizenswithgreateroversightofcompanies'taxpractices.
Thisproposal,whichiscurrentlybeingnegotiatedbytheCouncilandtheEuropeanParliament,shouldhelprestorepublicconfidenceincorporatetaxationandensurethatbusinessesarenotfacedwithapatchworkofnationalpublicdisclosurerules.
Aproposaltoallowtaxauthoritiesaccesstonationalanti-money1COM(2015)302final2COM(2016)451final3SeenoticeontheNotionofaid§169to174:http://ec.
europa.
eu/competition/state_aid/modernisation/notice_of_aid_en.
pdf4CouncilDirective(EU)2015/23765CouncilDirective(EU)2016/8813launderinginformation6isexpectedtobeagreedbeforetheendoftheyear.
TheEuropeanParliamentandCouncilhavealsostartedtoworkontheirpositionsonproposedamendmentstotheFourthAnti-MoneyLaunderingDirective,andshouldadvanceswiftlyfortriloguestobeginbyearly2017.
Inaddition,theCommissionhasstartedtoexaminethemostappropriateframeworktoimplementtheautomaticexchangeofinformationonbeneficialownership,atEuropeanlevel,andisexploringthebestwaytoincreaseoversightofenablersandpromotersofaggressivetaxplanningschemes.
ThisincreasedtaxtransparencyacrossEuropewillhelptoexposeaggressivetaxplanners,uncoverharmfultaxpracticesandstabiliseacorporatetaxenvironmentbuiltonopennessandtrust.
Inparallel,theCommissionisalsoworkingtoensurethatallcompaniesoperatingintheEUpaytheirtaxeswhereprofitsandvaluearegenerated.
Thisprincipleisessentialforfairandeffectivetaxation,butcanonlybeeffectivelyachievedinaSingleMarketthroughcommonandcoordinatedmeasures.
Therefore,theCommissionproposedanewAnti-TaxAvoidanceDirective7,settingoutlegally-bindinganti-abusemeasuresfortheentireEU,toblocksomeofthemostprevalentformsofbaseerosionandprofitshifting.
Thislegislation,whichMemberStatesadoptedinJuly2016,allowedMemberStatestoimplementinaswift,coordinatedandcoherentway,thecommitmentstheymadeundertheOECD/G20BaseErosionandProfitShifting(BEPS)project.
MemberStates'preferentialregimesandtransferpricingrulesarealsobeingreviewed,toensureacommonEUapproachtonewinternationalstandards.
ThisiscriticaltoprovidecertaintyforbusinessesasreformsareimplementedandtopreventnewloopholesemergingintheSingleMarket.
Finally,theCommissionhaspresentedmeasurestopromotetaxgoodgovernanceglobally,toensureafairandlevel-playingfieldbetweentheEUanditsinternationalpartners.
MemberStateshaveendorsedthenewExternalStrategyforEffectiveTaxation8,presentedbytheCommissioninJanuary2016,toprotecttheirtaxbasesagainstbaseerosionrisksfromabroad.
AkeycomponentofthisStrategyisanewEUlistingprocess,todealwithnon-cooperativetaxjurisdictionsandencourageallthirdcountryjurisdictionstomeetinternationaltaxgoodgovernancestandards.
ThefirststepsinthislistingprocesshavealreadybeentakenandthecommonEUlistshouldbefinalisedin2017.
ThiswillprovideMemberStateswithapowerfultooltodealwithcountriesthatrefusetoplayfairintaxmatters.
TheEU'sFinancialRegulationhasalsobeenrevisedtopreventEUfundsfrombeingroutedthroughtaxhavens,andworkisunderwaytostrengthenthetaxgoodgovernanceclausesinEUagreementswiththirdcountries.
3.
APOSITIVE,FORWARD-LOOKINGAGENDATheinitiativessetoutabovearevitaltoprotectMemberStates'taxbases,providealevel-playingfieldforbusinessesandensurefairandeffectivetaxationforalltaxpayers.
Theyaddressthemostpressingproblemsincorporatetaxationtoday.
However,forthelongerterm,thereisaneedtogofurther.
Shorttermfixescansoonbecomeoutdated,asbusinessmodelsandtaxplanningtechniquesevolvefasterthannewresponsescanbe6COM(2016)452final7CouncilDirective(EU)2016/11648COM(2016)24final4devised.
Inaddition,piecemealupdatestointernational,EUornationaltaxrulescreateturbulenceforboththetaxadministrationsandthebusinessesthatneedtoadapttothem.
Toboostjobs,growthandinvestment,itisnecessarytocreateafavourabletaxenvironmentforbusiness,byreducingcompliancecostsandadministrativeburdens,andbyensuringtaxcertainty.
TheimportanceoftaxcertaintyinpromotinginvestmentandgrowthhasrecentlybeenrecognisedbytheG20leaders,andhasbecomethenewglobalfocus.
MemberStatesneedtofindabalancebetweenimplementingnecessaryreformsandprovidingasteady,clearandpredictabletaxenvironmentforbusinesses.
TheEUneedsapositive,forward-lookingframeworkforcorporatetaxation.
Itmustbegrowth-friendly,efficientandfair,andfullysupporttheEU'swiderpolicypriorities,nowandinthefuture.
ThisistherationalebehindtheCommission'sproposaltore-launchtheCommonConsolidatedCorporateTaxBase(CCCTB).
TheCCCTBcanmeetthetwoprimarydemandsofbusinessesandcitizensinEuropetoday–sustainablegrowthandsocialjustice–andreinforcetheEU'soveralleconomicandsocialagenda.
Indeed,analysisshowsthattheCCCTBcanliftinvestmentintheEUbyupto3.
4%andgrowthby1.
2%9.
TheCommissionfirstproposedtheCCCTBin2011,withaviewtoenhancingtheSingleMarketforbusinesses.
Theproposalwasambitiousandrobust,butitsmagnitudelednegotiationsintheCounciltostall.
However,theEuropeanParliament,businesses,stakeholdersandmanyMemberStatesretainedstrongsupportfortheideaoftheCCCTB,giventhemanybenefitsithadtooffer.
Moreover,inthepastfewyears,ithasbecomeclearthattheCCCTBoffersmorethanjustabusiness-friendlytaxsystemforastrongerSingleMarket.
Therefore,intheJune2015ActionPlan,theCommissionannouncedthatitwouldre-launchthisimportantprojectthroughamoremanageabletwo-stepprocess.
Thefirststepfocussesonsecuringthecommonbase.
Oncethisisimplemented,themorecomplexaspectofconsolidationwillbeintroduced.
ManyofthemostimportantbenefitsoftheCCCTBliewiththeconsolidationaspect.
Therefore,thissecondstepinthere-launchedCCCTBcannotbeneglectedorputaside.
TheworkonthisPackagewillonlybecompleteoncethefullCCCTBisinplace.
There-launchoftheCCCTBprovidestheopportunitytoupdatetheoriginalproposalandalignitwithnewchallengesemergingintheglobaltaxenvironment.
ThemostnotablechangeisthattheCCCTBwillbemandatoryforallfinancialaccountinggroupswithconsolidatedgrouprevenuesofmorethanEUR750million.
Thisshouldhelptomaximiseitspotentialasananti-avoidancetool.
ItalsomeansthatbusinesseswillknowwheretheystandwhenitcomestotheEU'santi-abuserulesandwillnothavetomakeunnecessaryadjustments.
Assuch,itwillhelptocreateamorepredictableenvironmentforbusinessesintheEU.
TheCommissionhasalsointroducedtwonewelementsintotheproposalwhichdirectlysupporttheEU'swidereconomicagenda.
Researchanddevelopmentcostswillbegivenasuper-deduction,toencourageR&Dandinnovation,whicharekeydriversofgrowth.
Moreover,tosupportsmallandinnovativeentrepreneurship,anenhancedsuper-deductionwillbegiventosmallstartingcompanieswithoutassociatedenterprises.
TheCCCTBwillalsoaddressthedistortivepreferentialtreatmentofdebtcomparedtoequity,9ImpactAssessmentonaCommonConsolidatedCorporateTaxBase(CCCTB)[SWD(2016)341]5asacontributiontoastrongCapitalMarketsUnionandgreaterfinancialstabilityintheEU.
4.
MODERN,SIMPLE,CERTAIN:ABETTERANDMOREEFFICIENTTAXENVIRONMENTFORBUSINESSESBusinessesintheSingleMarketneedasimple,stableandlegallycertainenvironmentinwhichtothrive.
Theyshouldencounterminimaltaxobstacleswhenoperatingcross-borderandshouldnotbeburdenedbyunnecessaryadministrativeburdensandcosts.
TheEUneedsacorporatetaxframeworkadaptedtotherealitiesof21stcenturybusiness,whichencouragesenterprise,attractsinvestorsandfacilitatesallcompanies–bigandsmall.
4.
1ASingleCorporateTaxSystemForASingleMarketTheCCCTBwillconsiderablyimprovethefunctioningoftheSingleMarketfromataxperspective.
Cross-bordercompanieswillbenefitfromasinglesetofrulestocalculatetheirtaxableprofitsintheEU,ratherthanamedleyofdifferentnationalsystems.
TheywillbeabletofileasingletaxreturnforalltheirEUactivitiesthrougha"One-Stop-Shop"system,dealingwithjustoneMemberStateratherthanmultipletaxauthorities.
ConsolidationwillalsomeanthatlossesinoneMemberStatecanbeautomaticallysetoffagainstprofitsinanother,therebyallowingcross-bordercompaniestoenjoythesametreatmentaspurelydomesticones.
IntheproposedDirectivetore-launchtheCCCTB,theCommissionhaskeptthesameambitiousapproachtoconsolidationaswasintheoriginalproposal.
However,thetwo-stepapproachwilldelaythisadvantage.
Tocompensate,theCommissionhasproposedthat,untilconsolidationisagreed,companiesshouldhaveaccesstoasimple,robustandtemporarysystemofcross-borderlossoffsetwithinthecommonbase.
TheCCCTBwillbeclear,stableandboundinEUlaw.
ItwillbeunanimouslyagreedbyallMemberStates,guaranteeingastablesystemwhichisnotpronetoregularchanges.
Thiswillprovidebusinesseswithanunprecedentedleveloftaxcertainty.
CompanieswillnolongerhavetoadjusttothedivergenttaxrulesofeachMemberStateastheyexpandcross-border.
TheywillnolongerhavetostruggletounderstandMemberStates'differentapproachestotaxingcertainincome.
Theywillnolongersufferhighadministrativeandlegalcosts,todealwiththecomplexitiesoftransferpricing.
WiththeCCCTB,themaintaxobstaclesforbusinessesintheSingleMarkettodaywillberemoved.
TheCCCTBoffersmajorbenefitstosmallandmediumsizedenterprises(SMEs),aswellaslargecompanies,intheEU.
TheCCCTBwillonlybemandatoryforthelargestcompanies.
HoweverSMEsandstart-upscanoptintothesystemiftheywanttobenefitfromthesimplificationandcost-savingsitoffers.
Currently,SMEsareestimatedtospendaround30%oftaxespaidoncompliancecosts,andevenmoreiftheyexpandcross-border.
TheCCCTBwillcutthesecostssubstantiallyandreducetheexpenseofsettingupasubsidiaryinanotherMemberState.
Thesesavings,togetherwiththestreamlinedrulesandsimplertaxreturnsystem,willmakeitmucheasierforsmallandyoungcompaniestogrowandexpandintheSingleMarket.
64.
2ImprovedToolsToPreventDoubleTaxationCompaniesmustpaytheirfairshareoftaxwheretheymaketheirprofits,buttheyshouldnothavetopaymorethanthis.
OneofthebiggesttaxobstaclestotheSingleMarketisdoubletaxation.
DisagreementsamongstMemberStatesoverwhohastherighttotaxcertainprofitsoftenresultincompaniesbeingtaxedtwiceormoreonthesameincome.
Mostrecentfiguresindicatetherearearound900doubletaxationdisputesongoingintheEU,withEUR10.
5billionatstake.
MostMemberStateshavebilateraltaxtreatieswitheachother,torelievedoubletaxationandthereareprocedurestoresolvedisputes.
However,theseproceduresarelong,costlyanddonotalwaysresultinanagreement.
ThemultilateralArbitrationConvention,whichhasbeenagreedbetweenMemberStates,providessomerelief.
Howeveritsscopeislimitedtotransferpricingdisputesandthereisnorecoursetorepealtheinterpretationoftherules.
ForcompanieswithintheCCCTBsystem,doubletaxationshouldgenerallybecomeathingofthepast.
Asinglesetofrulestocalculatebusinessprofits,combinedwiththenewapportionmentformulathatclearlydistributestaxingrights,willmakeitclearwhatprofitsshouldbetaxedandwhere.
However,casesmaystillarise,forexamplewhentherearetransferpricingarrangementsbetweenagroupentitywithinandoutsidetheEU,andforcompaniesnotwithintheCCCTB.
Forthesecases,amoreefficientsystemofresolvingdoubletaxationdisputesisneeded.
Moreover,untiltheCCCTBisagreed,aneffectivesystemisneededmorewidelytoresolvedoubletaxationdisputes.
TheCommissionhastodayproposedaDirectivetoimproveDoubleTaxationDisputeResolutionMechanismsintheEU,toreinforceafairer,certainandmorestabletaxenvironment.
ThenewruleswillensurethatcasesofdoubletaxationareresolvedmorequicklyandmoredecisivelywhentheyarisebetweenMemberStates.
IfMemberStatescannotagreeonhowtoresolveacase,thetaxpayercanaskitsnationalcourttosetupanArbitrationCommitteetodeliverafinal,bindingdecisiononthecase,withinafixedtimeframe.
Thiswillhelptoavoidincertitudeforthebusinessesinvolved.
Awiderscopeofcaseswillalsobeabletobenefitfromtheresolutionmechanismsundertoday'sproposal.
TheseimprovementstoDisputeResolutionMechanismswillsavebothbusinessesandadministrationsaconsiderableamountoftime,moneyandresourcesandwillreinforcetaxcertaintyforcompaniesintheEU.
5.
TRANSPARENT,EFFECTIVE,COHERENT:FAIRERTAXATIONFORALLFairnesshasbecomeacentralrequirementforcorporatetaxpolicy,inEuropeandinternationally.
CompaniesthatbenefitfromtheSingleMarketmustpaytaxwheretheymaketheirprofitsandallcompaniesshouldbetreatedneutrallyfortaxpurposes.
TheEUneedsacorporatetaxsystemthatensuresrobustdefencesagainstcorporatetaxabuse,alevel-playingfieldforbusinessesandfairburden-sharingforalltax-payers.
5.
1AFairerCorporateTaxSystemTheCCCTBistheembodimentofafaircorporatetaxsystem.
Itwilladdressimportantweaknessesinthecurrenttaxframeworkwhichenableaggressivetaxplanning.
Itwillremovemismatchesandloopholesbetweennationaltaxsystems,whichareexploitedbytaxavoiders,asallMemberStateswillapplythesamerulesfor7calculatingcompanies'taxableprofits.
Transferpricing,whichaccountsforaround70%ofallprofit-shifting,willbeeliminated.
Moreover,tostrengthentheanti-avoidancecapacityoftheCCCTB,itwillbemandatoryforthelargestcompaniesoperatingintheEU.
TheincentiveforMemberStatestoengageinharmfultaxcompetitionwillberemoved.
MemberStateswillnolongerneedtodevotelargeresourcestochasingmobiletaxbases,becausetheCCCTBapportionsprofitstoensurethattaxationbetterreflectswheretherealeconomicactivitytakesplace.
ThiswillallowMemberStatestore-focustheirresourcesongrowth-friendlytaxation,whichincentivisesinvestmentandemploymentandsupportswidersocio-economicneeds.
TheCCCTBwillalsointroducecompletetransparencyoneachMemberState'ssystemandtheireffectivetaxrates.
MemberStateshaveasovereignrighttosettheirowntaxratesandtheCCCTBdoesnotcompromisethisinanyway.
However,itwillensurethatwhenaMemberStatesdecidesonitstaxrate,thisrateistheneffectivelyappliedtoallcompanies.
Hiddenpreferentialregimesandharmfultaxrulingswillnolongerbepossible.
Thisshouldincreasecitizens'confidenceinthewaycompaniesaretaxedandensureamorelevel-playingfieldforallcompaniesintheSingleMarket.
5.
2FurtherAnti-AbuseMeasuresTheCCCTBcontainsanti-abuseprovisionstoprotectMemberStatesagainstbaseerosionandprofitshifting,bothwithintheEUandwithrespecttothirdcountries.
Thiswillreinforceitsimpactasaninstrumenttopreventtaxavoidance.
Theanti-abusemeasureswithintheCCCTBmirrorthoseintheAntiTaxAvoidanceDirective(ATAD),whichwereagreedbyMemberStatesinJuly2016.
Thiswillensurethatallcompaniesaresubjecttothesameanti-abuserules,whethertheyareinsidetheCCCTBsystemornot.
TheCommissionhasalsopresentedanotherproposaltodaytotacklehybridmismatchesinvolvingthirdcountries,tofurtherreinforceEUanti-abuseprovisionsandaddressexternalrisks.
TheAnti-TaxAvoidanceDirective(ATAD)alreadydealswithhybridmismatcheswithintheEU,eliminatingamajorchannelofbaseerosionandprofit-shifting.
However,thesemismatchesarenotlimitedtotheSingleMarketandasolutionisneededtocounter-actexternalrisks.
WhenagreeingontheATAD,MemberStatesaskedtheCommissiontobringforwardanotherproposal,toensurethatthisgapiseffectivelyaddressed.
TheCommissionhasthereforeproposednewmeasurestoaddressabroadrangeofmismatches,includinghybridpermanentestablishmentmismatches,importedmismatches,hybridtransfersanddualresidentmismatches,bothwithintheEUandinrelationtothird-countries.
LikethemeasuresintheATAD,therulesinthisnewproposalareinlinewiththeOECDBEPSapproach.
6.
STABLE,SUPPORTIVE,UNBIASED:AMODERNTAXSYSTEMFORAHEALTHYECONOMYTheEUneedsacorporatetaxsystemshapedtosupportamorecompetitive,innovativeandeconomically-stableEU.
Growthandinvestmentrelyonanenvironmentthatenablesbusiness,encouragesproductivefinancingandrewardsgrowth-friendlyactivitiessuchasresearchandinnovation.
TheCCCTBwillmaketheEUahighlyattractivemarkettoinvestin,byofferingcompaniessolidandpredictablerules,alevel-playingfield,andreducedcostsandadministration.
Inaddition,theCommissionhasreinforcedthe8CCCTBproposalwithnewprovisionsthatspecificallyfocusongrowth-promotingactivities.
6.
1BetterIncentivesforInnovationTheCCCTBwillsupportResearchandDevelopment,whicharekeydriversofgrowthandcompetitiveness.
Currently,theEUisfallingbehindotheradvancedeconomieswhenitcomestoinvestmentinresearchandinnovation.
AlthoughnearlyallMemberStateshavesometaxincentiveforR&D,notalloftheseareeffectiveandsomeareevenexploitedbylargerfirmsfortaxavoidancepurposes.
DivergentnationalincentivesalsocreateacomplextaxenvironmentforcompaniesinvestinginR&D.
TheCCCTBwillofferanEU-widetaxdeductiontocompaniesthatinvestinrealresearchactivities.
Thisdeductionwillbeevenmoregenerousforstart-upcompanies,giventheirimportanceinjobcreation,thepromotionofhealthycompetitionandtheestablishmentofmoreefficientbusinessmodels.
TheR&Dincentivewillgiveaboosttocompanieswithsmallerbudgets,toallowthemtogrow,andwillencouragethecreationandexpansionofyoung,innovativeenterprises.
Itisalsodesignedonthebasisofabestpracticemodel,sothatitcan'tbeusedforavoidancepurposes.
6.
2AnInvestment-FriendlyTaxEnvironmentTheCCCTBwillalsoaddressdistortionsincurrenttaxsystemsthatcandestabilisetheeconomy.
MostMemberStates'corporatetaxsystemsfavourdebtbyallowinginterestpaymentstobededucted,withoutgrantingsimilartreatmenttoequity.
Thispreferentialtreatmentencouragescompaniestotakeonmoredebt,makingthemmorefragileandmakingeconomiesmorepronetocrises.
ThispresentsanobstacletothecreationofastrongerequitybaseinEuropeancompanies.
Ittiltsthestructureofthefinancialmarkettowardsdebtinstrumentsandmayimpedeefficientcapitalmarketfinancing.
ThisgoesagainstthefundamentalgoalsoftheCapitalMarketsUnionandthecapitalbaserequirementsfortheBankingUnion.
TheCCCTBwillremovethedebtbiasdistortion,byofferinganAllowanceforGrowthandInvestment(AGI).
Thisallowancewillensurethatequityreceivesasimilarleveloftaxbenefitsasdebtdoes,creatingamoreneutralandinvestment-friendlytaxenvironment.
TheAGIwillrewardcompaniesthatstrengthentheirfinancingstructuresandtapintocapitalmarkets10.
SMEs,thatoftenstruggletosecureloans,willparticularlybenefitfromthisnewprovision.
GiventhepositiveimpactthattheAGIwillhaveonbothbusinessesandthewidereconomy,theCommissionalsoinvitesMemberStatetoconsiderusingitforcompaniesoutsidetheCCCTBsystemtoo.
7.
CONCLUSIONTheCommissionisproposingacomprehensiveresponsetocurrentandemergingchallengesincorporatetaxationandapositivenewapproachtotaxingcompaniesinthefuture.
TheCCCTBwilldelivernotableimprovementstotheEU'scorporatetaxframework,intermsofsimplicity,taxcertaintyandfairness.
Itwillensurethatcorporate10Giventhehigherriskslinkedtoequityfinancingcomparedtodebtfinancing,ariskpremiumwillbeaddedtotheyieldfordeterminingtheamountfordeduction.
Giventhatincreasesintheequitybasemaygoback10years,thereferenceyieldfordeductionwillbethe10-yeargovernmentbenchmarkbondintheeuroarea.
9taxationisalignedtothemoderneconomyandthatitsupportsthegoalofastrongerandmorecompetitiveSingleMarket.
TheproposalonDoubleTaxationDisputeResolutionandtheproposaltotacklehybridmismatcheswiththirdcountries,whichtheCommissionhasalsopresentedtoday,willfurthercontributetofairerandmoreefficientcorporatetaxationintheEU.
TheCommissionthereforecallsonMemberStatestoswiftlyagreeonalloftheproposalspresentedtoday,sothatbusinesses,administrations,citizensandtheEuropeaneconomycanstarttoenjoythefulladvantagesofthisfair,competitiveandstablecorporatetaxenvironment.
- promotefilemarkets.com相关文档
- Imagefilemarkets.com
- grantedfilemarkets.com
- householdsfilemarkets.com
- indexesfilemarkets.com
- tierfilemarkets.com
- Sourcefilemarkets.com
昔日数据月付12元起,湖北十堰机房10M带宽月付19元起
昔日数据怎么样?昔日数据是一个来自国内服务器销售商,成立于2020年底,主要销售国内海外云服务器,目前有国内湖北十堰云服务器和香港hkbn云服务器 采用KVM虚拟化技术构架,湖北十堰机房10M带宽月付19元起;香港HKBN,月付12元起; 此次夏日活动全部首月5折促销,有需要的可以关注一下。点击进入:昔日数据官方网站地址昔日数据优惠码:优惠码: XR2021 全场通用(活动持续半个月 2021/7...
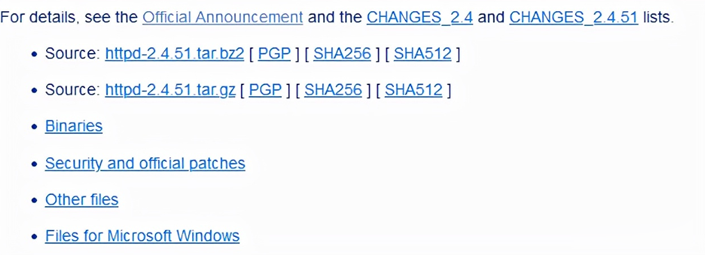
新版本Apache HTTP Server 2.4.51发布更新(有安全漏洞建议升级)
今天中午的时候看到群里网友在讨论新版本的Apache HTTP Server 2.4.51发布且建议更新升级,如果有服务器在使用较早版本的话可能需要升级安全,这次的版本中涉及到安全漏洞的问题。Apache HTTP 中2.4.50的修复补丁CVE-2021-41773 修复不完整,导致新的漏洞CVE-2021-42013。攻击者可以使用由类似别名的指令配置将URL映射到目录外的文件的遍历攻击。这里...
RAKsmart 黑色星期五云服务器七折优惠 站群服务器首月半价
一年一度的黑色星期五和网络星期一活动陆续到来,看到各大服务商都有发布促销活动。同时RAKsmart商家我们也是比较熟悉的,这次是继双十一活动之后的促销活动。在活动产品中基本上沿袭双11的活动策略,比如有提供云服务器七折优惠,站群服务器首月半价、还有新人赠送红包等活动。如果我们有需要RAKsmart商家VPS、云服务器、独立服务器等产品的可以看看他们家的活动。这次活动截止到11月30日。第一、限时限...
filemarkets.com为你推荐
-
京沪高铁上市首秀在中国股市中:京沪高铁概念股有哪些对对塔今儿老师给推荐了一个叫对对塔的学习网站,看起来挺不错的,有用过的人吗?管不管用?哪些功能比较好啊?sherylsandberg谷歌怎么看自己的详细资料lunwenjiance论文检测,知网的是32.4%,改了以后,维普的是29.23%。如果再到知网查,会不会超过呢?www.yahoo.com.hk香港的常用网站www.zjs.com.cn我的信用卡已经申请成功了,显示正在寄卡,怎么查询寄卡信息?国风商讯国风塑钢质量怎么样猴山条约关于猴的谚语酒仙琐事"酒仙"指的是什么人?chudian365舒思盾按摩器怎么样用起像触电