electronicwww
www.e12.com.cn 时间:2021-03-01 阅读:()
www.
pkf-hk.
comNewPoliciesforDeepeningtheValue-addedTax("VAT")ReformPKFHONGKONG|TAXPKFHONGKONG|TAXBackgroundOn5March2019,PremierLiKeqiangproposedinthe"GovernmentWorkReport"thatthePRC'sGovernmentwillimplementlarger-scaletaxreductionpoliciesanddeepentheVATreform.
On20March2019,PremierLiKeqiangchairedtheExecutiveMeetingsoftheStateCouncilandclarifiedthesupportingmeasuresforVATtaxreduction.
On21March2019,theMinistryofFinance,theStateTaxationAdministrationandtheGeneralAdministrationofCustomsjointlyissuedthe"AnnouncementonPoliciesforDeepeningtheVATReform"(Announcement[2019]No.
39oftheMinistryofFinance,theStateTaxationAdministrationandtheGeneralAdministrationofCustoms)("AnnouncementNo.
39")andseveralguidelinesinordertoreducetheVATtaxburden.
AnnouncementNo.
39hascomeintoeffecton1April2019.
WesetoutbelowanoverviewandkeymeasuresofAnnouncementNo.
39.
OverviewofAnnouncementNo.
391.
ReductionofVATratesWhenVATgeneraltaxpayers("thetaxpayers")carryoutVATtaxableactivitiesorimportsgoods,theapplicableVATrateshavebeenreducedasfollows:theoriginalVATrate16%forrelevanttransactionsisadjustedto13%;theoriginalVAT10%forrelevanttransactionsisadjustedto9%;andtheoriginalVATrate6%forrelevanttransactionsremainsunchanged.
Wherethereisaneedtocorrectorissueaninvoiceforthetaxableactivitiesoccurredbefore1April2019,theinvoiceshallbeissuedaccordingtotheoriginalapplicableVATratesanditisprohibitedtoapplythenewVATrates.
2.
ReductionofexportrefundratesInlinewiththereductionofVATrates,thePRCenterpriseexportrefundrateandtheoverseasvisitorspurchaserefundrateupontheirdeparturehavebeenreducedaccordinglyasfollowing:-AdjustedrefundrateExportedgoodsandrelevantservicewhichareoriginallysubjectto16%VATrateand16%exportrefundrateExportrefundrateisadjustedto13%Exportedgoodsandcrossboardertaxableactivitieswhichareoriginallysubjectto10%VATrateand10%exportrefundrateExportrefundrateisadjustedto9%Thegoodspurchasedbyoverseasvisitorswhicharesubjecttoa13%refundrateRefundrateisadjustedto11%Thegoodspurchasedbyoverseasvisitorswhicharesubjecttoa9%refundrateRefundrateisadjustedto8%PleasenotethatifthetaxpayershadpaidtheVATbasedontheoriginalVATratebefore30June2019,theoriginalrefundrateshallapply;ifthetaxpayerspaidtheVATbasedonthenewVATrate,thenewrefundrateshallapply.
PKFHONGKONG|TAXOverviewofAnnouncementNo.
393.
Reductionofagriculturalproducts'deductionrateForagriculturalproductspurchasedbytaxpayers,thenewdeductionrateisadjustedto9%fromtheoriginalrate10%.
ForagriculturalproductspurchasedbytaxpayersforproductionoroutsourcedprocessingwhicharesubjecttoVATat13%,a10%deductionrateshallapplywhencalculatinginputVAT.
4.
One-offdeductionofinputVATarisingfromtheacquisitionofimmovablepropertyorprojectunderconstructionTaxpayersnolongerneedtoclaimtheirinputVATcreditforpurchasingimmovablepropertyorprojectunderconstructionover2years.
AllrelevantinputVATcannowbedeductedintherelevanttaxperiod.
BeforethecommencementofAnnouncementNo.
39,ifthereisanyinputVATnotyetfullydeducted,itcanbeusedtooffsettheoutputVATintherelevanttaxperiodstartingfromApril2019.
5.
InputVATforpurchaseofdomesticpassengertransportationservicesAnnouncementNo.
39hasrevisedtherelevantprovisionsinthepreviousVATregulationsfor"certaintypesofserviceswhoseinputVATcannotbeclaimed",andstipulatesthatifthetaxpayerspurchase"domesticpassengertransportationservices",theinputVATarisingfromsuchservicescanbeusedtooffsetthetaxpayers'outputVAT.
IfthetaxpayersobtainVATelectronicgeneralinvoicesorVATspecialinvoices,theinputVATshallbetheVATamountindicatedontheinvoices;iftaxpayersobtaindocumentswhichstatethepassenger'sidentityinformationincludingairtransporte-ticket,railwaytickets,roadorwaterwayticketandetc.
,theinputVATshallbecalculatedbytheVATinclusivepriceonsuchdocumentsandapplicableVATrates.
PKFHONGKONG|TAXOverviewofAnnouncementNo.
396.
SuperdeductionofinputVATforseveralindustriesFrom1April2019to31December2021,taxpayersengagedinproductionorlivelihoodrelatedserviceswillbegranteda10%superdeductionofinputVATtooffsettheirVATpayable("SuperDeductionPolicy").
Applicablescope:"taxpayersengagedinproductionorlivelihoodrelatedservices"referstoanytaxpayerswhichearnmorethan50%oftheirtotalsalesrevenuebyprovidingpostalservice,telecommunicationsservice,modernserviceorlifestyleservice.
Thespecificrulesareasfollows:-1.
Forthosetaxpayersincorporatedbefore31March2019,ifthesalesamountfromApril2018toMarch2019meetsrelevantrequirement(iftheoperationperiodislessthan12month,theactualsalesamountisregardedasthesalesamount),theSuperDeductionPolicyshallapplysince1April2019.
2.
Forthosetaxpayersincorporatedafter1April2019,ifthesalesamountsinceincorporationmeetsrelevantrequirement,theSuperDeductionPolicyshallapplyfromthedateofregistrationtobeageneralVATtaxpayer.
3.
Oncethetaxpayersconfirmtoapplythesuperdeduction,noadjustmentshallbemadeinthecurrentyear,andtheireligibilityforthesuperdeductioninthefollowingyearshouldbedeterminedbasedonitssalesamountoftheprecedingyear.
Ataxpayershouldmakethesuperdeductioninthecurrentperiodat10%ofthecurrentperiod'screditableinputVAT.
Nosupperdeductionshallbecalculatedfornon-deductibleinputVATaccordingtotheprevailingregulations.
IftheinputVATistransferredoutasrequired,thesuperdeductionrelatedtosuchamountofinputVATshouldalsobereducedaccordinglyinthecurrentperiod.
Theformulaofcalculatingthesuperdeductionisasbelow:Superdeductionprovisioninthecurrentperiod=creditableinputVATincurrentperiod*10%Superdeductionamountdeductibleinthecurrentperiod=balanceofsuperdeductionattheendofthepreviousperiod+superdeductionprovisioninthecurrentperiod–superdeductionamountreductioninthecurrentperiodPKFHONGKONG|TAXOverviewofAnnouncementNo.
397.
VATrefundsforexcessinputVATThepilotsystemforrefundingtheexcessinputVATcreditshastakeneffecton1April2019.
AtaxpayerwhomeetsallofthefollowingcriteriamayapplyfortherefundofitsincrementalexcessinputVAT:1.
FromthetaxperiodsinceApril2019,theincrementalexcessinputVATforeachofthesixconsecutivemonths(twoconsecutivequartersiftaxedquarterly)isapositiveamount,andtheincrementalexcessinputVATcreditsinthesixthmonthisnotlessthanRMB500,000;2.
Thetaxpayer'staxationcreditrankingisratedasGradeAorGradeB;3.
ThetaxpayerhasnotcommittedfraudforexcessinputVATrefund,exportrefundorfalselyissuedspecialVATinvoicesfor36monthsbeforeitsclaimfortheVATrefund;4.
Thetaxpayerhasnotbeenpenalizedbytaxauthoritiesfortaxevasionmattersfortwoormoretimeswithin36monthsbeforeitsclaimfortheVATrefund;and5.
IthasnotenjoyedthepolicyofVATrefundundertherefund-upon-levyorrefund-after-levysince1April2019.
TheformulaoftherefundableamountregardingincrementalexcessinputVATinthecurrentperiodisasfollows:RefundableincrementalexcessinputVAT=incrementalexcessinputVAT*theproportionofinputVAT*60%ProportionofinputVATreferstotheproportionofVATindicatedinthespecialVATinvoices(includingthemachine-printeduniforminvoicesformotorvehiclesales)thathavebeencredited,specialVATpaymentformsissuedbyCustomsforimportandtaxpaymentreceiptsfromApril2019untiltheprecedingtaxperiodoftheclaimforVATrefund,overallinputVATthathasbeencreditedinthesameperiods.
Fortheexportofgoodsandlaborservicesorcross-bordertaxableactivitiescarriedoutbyataxpayer,towhichthemeasuresforVAT"exemption,creditandrefund"areapplicable,thetaxpayercouldapplyfortherefundoftheexcessinputVATcreditsgiventhatitstillmeetsthecriteriaspecifiedinAnnouncementNo.
39aftercompletingtheformalitiesforVAT"exemption,creditorrefund";ifthemeasuresforVAT"exemptionandrefund"areapplicable,therelevantinputVATshouldnotbeusedfortherefundofexcessinputVAT.
PKFHONGKONG|TAXPKFCommentsTaxreductionisthekeyreformdirectionofthePRC'sfinancialdepartmentinrecentyears.
ThedeepeningVATreformpolicythistimefocusesonreducingtheVATratesofcertainindustriessuchasmanufacturing,transportation,constructionandbasictelecommunicationsservices,butitdoesnotreducethe6%VATrateapplicabletotheserviceindustry.
WeviewthatitispossibleforthePRCgovernmenttosimplifythethree-levelVATratesinthefutureinordertoachievethesimplificationoftaxationsystem.
Itisunlikelythatthe6%VATratewillbereducedinthefollowingyears,butthereisstillroomforsimplificationofthethree-levelVATratesafterthisreform.
Thereductionofthetaxratewouldsignificantlyreducethetaxburdenofintermediateflowsofgoodsorservices,andwouldlaythefoundationforthegovernment'smacroscopicpolicyofreducingtaxburden.
TaxpayersshouldfocusontheeffectivedateoftheVATreformpolicy.
SincethetimingwhentheVATobligationarisesmaynotbeconsistentwiththetimingofrevenuerecognition,ifthetaxpayerscandeterminethetimingofVATobligationandtheapplicableVATratesmoreaccuratelyinadvance,theyshouldbeabletomitigaterelevanttaxrisksinareasonablemanner.
TheVATreductionpolicies(includingthepilotsystemofVATrefundsforexcessinputVAT)underAnnouncementNo.
39caneffectivelyincreasetaxpayers'cashflow,reducetaxpayers'operatingcostsandcreatelargerprofitmarginsfortaxpayers.
Taxpayersshouldmakeproperpreparationsfortheabovepreferentialpoliciestoensurethattheycanfullyenjoythepreferentialtaxpoliciesbyevaluatingtheirsituation,improvingtheinternalcontrolsystemandperformingreasonabletaxplanning.
Moreover,theVATreductionpoliciesthistimearealsoinlinewiththeinternaltrendofreducingtaxburden.
Fromthedomesticperspective,weviewthatthetaxreductionpolicieswouldbebeneficialtothedevelopmentofPRC'seconomyandcross-bordertrading,andwouldbeabletoattractmoreforeigninvestmentinthePRC.
PKFHONGKONG|TAX2019PKFHongKongLimited|AllRightsReservedPKFHongKongLimitedisamemberfirmofthePKFInternationalLimitedfamilyoflegallyindependentfirmsanddoesnotacceptanyresponsibilityorliabilityfortheactionsorinactionsofanyindividualmemberorcorrespondentfirmorfirms.
JeffreyLauTaxManagerjeffreylau@pkf-hk.
comHenryFungTaxPartnerhenryfung@pkf-hk.
comlinkedin.
com/company/pkf-hong-kong/https://www.
facebook.
com/PKFhkIMPORTANTNOTE:Theinformationcontainedinthisdocumentisonlyforgeneralinformationandisnotintendedtoaddressthecircumstancesofanyparticularentitiesorindividuals.
Accordingly,thisdocumentdoesnotconstituteaccounting,tax,legal,investment,consulting,orotherprofessionaladviceorservices.
Noactionshouldbetakensolelyonthebasisofthecontentsofthisdocumentwhichonlycontainabriefoutlineoftherelevantlaws.
Beforetakinganyaction,pleaseensurethatyouobtainadvicespecifictoyourcircumstancesfromyourusualPKFtaxpartnersorothertaxadvisersorliaisewiththerelevanttaxauthorities.
Weacceptnoresponsibilityorliabilitytoanypersonschoosingtotakeactionorimplementbusinessplansoractivitiessolelyorpartiallybasedonthisdocument.
PKFHongKongLimited26/F,CiticorpCentre,18WhitfieldRoad,CausewayBay,HongKongPKFconsistsofover400offices,operatingin150countriesacrossfiveregions.
Wespecialiseinprovidinghighqualityaudit,accounting,tax,andbusinessadvisorysolutionstointernationalanddomesticorganisationsinallourmarkets.
PKFTaxandBusinessAdvisoryprovidescomprehensivetaxandbusinessadvisoryservicesinrespectoftheInternational,HongKongandChinataxmatters.
OurprofessionalteamatPKFHongKongisexperiencedinprovidingcross-borderindividualincometaxadviceinvolvingHongKongandChina.
Ifyourequireassistanceinthisregard,pleasefeelfreetocontactus.
Contactus:FollowusonWeChatScantheQRcodeandgetthelatestPKFHongTel:+85228063822Email:enquiry@pkf-hk.
comWebsite:www.
pkf-hk.
com
pkf-hk.
comNewPoliciesforDeepeningtheValue-addedTax("VAT")ReformPKFHONGKONG|TAXPKFHONGKONG|TAXBackgroundOn5March2019,PremierLiKeqiangproposedinthe"GovernmentWorkReport"thatthePRC'sGovernmentwillimplementlarger-scaletaxreductionpoliciesanddeepentheVATreform.
On20March2019,PremierLiKeqiangchairedtheExecutiveMeetingsoftheStateCouncilandclarifiedthesupportingmeasuresforVATtaxreduction.
On21March2019,theMinistryofFinance,theStateTaxationAdministrationandtheGeneralAdministrationofCustomsjointlyissuedthe"AnnouncementonPoliciesforDeepeningtheVATReform"(Announcement[2019]No.
39oftheMinistryofFinance,theStateTaxationAdministrationandtheGeneralAdministrationofCustoms)("AnnouncementNo.
39")andseveralguidelinesinordertoreducetheVATtaxburden.
AnnouncementNo.
39hascomeintoeffecton1April2019.
WesetoutbelowanoverviewandkeymeasuresofAnnouncementNo.
39.
OverviewofAnnouncementNo.
391.
ReductionofVATratesWhenVATgeneraltaxpayers("thetaxpayers")carryoutVATtaxableactivitiesorimportsgoods,theapplicableVATrateshavebeenreducedasfollows:theoriginalVATrate16%forrelevanttransactionsisadjustedto13%;theoriginalVAT10%forrelevanttransactionsisadjustedto9%;andtheoriginalVATrate6%forrelevanttransactionsremainsunchanged.
Wherethereisaneedtocorrectorissueaninvoiceforthetaxableactivitiesoccurredbefore1April2019,theinvoiceshallbeissuedaccordingtotheoriginalapplicableVATratesanditisprohibitedtoapplythenewVATrates.
2.
ReductionofexportrefundratesInlinewiththereductionofVATrates,thePRCenterpriseexportrefundrateandtheoverseasvisitorspurchaserefundrateupontheirdeparturehavebeenreducedaccordinglyasfollowing:-AdjustedrefundrateExportedgoodsandrelevantservicewhichareoriginallysubjectto16%VATrateand16%exportrefundrateExportrefundrateisadjustedto13%Exportedgoodsandcrossboardertaxableactivitieswhichareoriginallysubjectto10%VATrateand10%exportrefundrateExportrefundrateisadjustedto9%Thegoodspurchasedbyoverseasvisitorswhicharesubjecttoa13%refundrateRefundrateisadjustedto11%Thegoodspurchasedbyoverseasvisitorswhicharesubjecttoa9%refundrateRefundrateisadjustedto8%PleasenotethatifthetaxpayershadpaidtheVATbasedontheoriginalVATratebefore30June2019,theoriginalrefundrateshallapply;ifthetaxpayerspaidtheVATbasedonthenewVATrate,thenewrefundrateshallapply.
PKFHONGKONG|TAXOverviewofAnnouncementNo.
393.
Reductionofagriculturalproducts'deductionrateForagriculturalproductspurchasedbytaxpayers,thenewdeductionrateisadjustedto9%fromtheoriginalrate10%.
ForagriculturalproductspurchasedbytaxpayersforproductionoroutsourcedprocessingwhicharesubjecttoVATat13%,a10%deductionrateshallapplywhencalculatinginputVAT.
4.
One-offdeductionofinputVATarisingfromtheacquisitionofimmovablepropertyorprojectunderconstructionTaxpayersnolongerneedtoclaimtheirinputVATcreditforpurchasingimmovablepropertyorprojectunderconstructionover2years.
AllrelevantinputVATcannowbedeductedintherelevanttaxperiod.
BeforethecommencementofAnnouncementNo.
39,ifthereisanyinputVATnotyetfullydeducted,itcanbeusedtooffsettheoutputVATintherelevanttaxperiodstartingfromApril2019.
5.
InputVATforpurchaseofdomesticpassengertransportationservicesAnnouncementNo.
39hasrevisedtherelevantprovisionsinthepreviousVATregulationsfor"certaintypesofserviceswhoseinputVATcannotbeclaimed",andstipulatesthatifthetaxpayerspurchase"domesticpassengertransportationservices",theinputVATarisingfromsuchservicescanbeusedtooffsetthetaxpayers'outputVAT.
IfthetaxpayersobtainVATelectronicgeneralinvoicesorVATspecialinvoices,theinputVATshallbetheVATamountindicatedontheinvoices;iftaxpayersobtaindocumentswhichstatethepassenger'sidentityinformationincludingairtransporte-ticket,railwaytickets,roadorwaterwayticketandetc.
,theinputVATshallbecalculatedbytheVATinclusivepriceonsuchdocumentsandapplicableVATrates.
PKFHONGKONG|TAXOverviewofAnnouncementNo.
396.
SuperdeductionofinputVATforseveralindustriesFrom1April2019to31December2021,taxpayersengagedinproductionorlivelihoodrelatedserviceswillbegranteda10%superdeductionofinputVATtooffsettheirVATpayable("SuperDeductionPolicy").
Applicablescope:"taxpayersengagedinproductionorlivelihoodrelatedservices"referstoanytaxpayerswhichearnmorethan50%oftheirtotalsalesrevenuebyprovidingpostalservice,telecommunicationsservice,modernserviceorlifestyleservice.
Thespecificrulesareasfollows:-1.
Forthosetaxpayersincorporatedbefore31March2019,ifthesalesamountfromApril2018toMarch2019meetsrelevantrequirement(iftheoperationperiodislessthan12month,theactualsalesamountisregardedasthesalesamount),theSuperDeductionPolicyshallapplysince1April2019.
2.
Forthosetaxpayersincorporatedafter1April2019,ifthesalesamountsinceincorporationmeetsrelevantrequirement,theSuperDeductionPolicyshallapplyfromthedateofregistrationtobeageneralVATtaxpayer.
3.
Oncethetaxpayersconfirmtoapplythesuperdeduction,noadjustmentshallbemadeinthecurrentyear,andtheireligibilityforthesuperdeductioninthefollowingyearshouldbedeterminedbasedonitssalesamountoftheprecedingyear.
Ataxpayershouldmakethesuperdeductioninthecurrentperiodat10%ofthecurrentperiod'screditableinputVAT.
Nosupperdeductionshallbecalculatedfornon-deductibleinputVATaccordingtotheprevailingregulations.
IftheinputVATistransferredoutasrequired,thesuperdeductionrelatedtosuchamountofinputVATshouldalsobereducedaccordinglyinthecurrentperiod.
Theformulaofcalculatingthesuperdeductionisasbelow:Superdeductionprovisioninthecurrentperiod=creditableinputVATincurrentperiod*10%Superdeductionamountdeductibleinthecurrentperiod=balanceofsuperdeductionattheendofthepreviousperiod+superdeductionprovisioninthecurrentperiod–superdeductionamountreductioninthecurrentperiodPKFHONGKONG|TAXOverviewofAnnouncementNo.
397.
VATrefundsforexcessinputVATThepilotsystemforrefundingtheexcessinputVATcreditshastakeneffecton1April2019.
AtaxpayerwhomeetsallofthefollowingcriteriamayapplyfortherefundofitsincrementalexcessinputVAT:1.
FromthetaxperiodsinceApril2019,theincrementalexcessinputVATforeachofthesixconsecutivemonths(twoconsecutivequartersiftaxedquarterly)isapositiveamount,andtheincrementalexcessinputVATcreditsinthesixthmonthisnotlessthanRMB500,000;2.
Thetaxpayer'staxationcreditrankingisratedasGradeAorGradeB;3.
ThetaxpayerhasnotcommittedfraudforexcessinputVATrefund,exportrefundorfalselyissuedspecialVATinvoicesfor36monthsbeforeitsclaimfortheVATrefund;4.
Thetaxpayerhasnotbeenpenalizedbytaxauthoritiesfortaxevasionmattersfortwoormoretimeswithin36monthsbeforeitsclaimfortheVATrefund;and5.
IthasnotenjoyedthepolicyofVATrefundundertherefund-upon-levyorrefund-after-levysince1April2019.
TheformulaoftherefundableamountregardingincrementalexcessinputVATinthecurrentperiodisasfollows:RefundableincrementalexcessinputVAT=incrementalexcessinputVAT*theproportionofinputVAT*60%ProportionofinputVATreferstotheproportionofVATindicatedinthespecialVATinvoices(includingthemachine-printeduniforminvoicesformotorvehiclesales)thathavebeencredited,specialVATpaymentformsissuedbyCustomsforimportandtaxpaymentreceiptsfromApril2019untiltheprecedingtaxperiodoftheclaimforVATrefund,overallinputVATthathasbeencreditedinthesameperiods.
Fortheexportofgoodsandlaborservicesorcross-bordertaxableactivitiescarriedoutbyataxpayer,towhichthemeasuresforVAT"exemption,creditandrefund"areapplicable,thetaxpayercouldapplyfortherefundoftheexcessinputVATcreditsgiventhatitstillmeetsthecriteriaspecifiedinAnnouncementNo.
39aftercompletingtheformalitiesforVAT"exemption,creditorrefund";ifthemeasuresforVAT"exemptionandrefund"areapplicable,therelevantinputVATshouldnotbeusedfortherefundofexcessinputVAT.
PKFHONGKONG|TAXPKFCommentsTaxreductionisthekeyreformdirectionofthePRC'sfinancialdepartmentinrecentyears.
ThedeepeningVATreformpolicythistimefocusesonreducingtheVATratesofcertainindustriessuchasmanufacturing,transportation,constructionandbasictelecommunicationsservices,butitdoesnotreducethe6%VATrateapplicabletotheserviceindustry.
WeviewthatitispossibleforthePRCgovernmenttosimplifythethree-levelVATratesinthefutureinordertoachievethesimplificationoftaxationsystem.
Itisunlikelythatthe6%VATratewillbereducedinthefollowingyears,butthereisstillroomforsimplificationofthethree-levelVATratesafterthisreform.
Thereductionofthetaxratewouldsignificantlyreducethetaxburdenofintermediateflowsofgoodsorservices,andwouldlaythefoundationforthegovernment'smacroscopicpolicyofreducingtaxburden.
TaxpayersshouldfocusontheeffectivedateoftheVATreformpolicy.
SincethetimingwhentheVATobligationarisesmaynotbeconsistentwiththetimingofrevenuerecognition,ifthetaxpayerscandeterminethetimingofVATobligationandtheapplicableVATratesmoreaccuratelyinadvance,theyshouldbeabletomitigaterelevanttaxrisksinareasonablemanner.
TheVATreductionpolicies(includingthepilotsystemofVATrefundsforexcessinputVAT)underAnnouncementNo.
39caneffectivelyincreasetaxpayers'cashflow,reducetaxpayers'operatingcostsandcreatelargerprofitmarginsfortaxpayers.
Taxpayersshouldmakeproperpreparationsfortheabovepreferentialpoliciestoensurethattheycanfullyenjoythepreferentialtaxpoliciesbyevaluatingtheirsituation,improvingtheinternalcontrolsystemandperformingreasonabletaxplanning.
Moreover,theVATreductionpoliciesthistimearealsoinlinewiththeinternaltrendofreducingtaxburden.
Fromthedomesticperspective,weviewthatthetaxreductionpolicieswouldbebeneficialtothedevelopmentofPRC'seconomyandcross-bordertrading,andwouldbeabletoattractmoreforeigninvestmentinthePRC.
PKFHONGKONG|TAX2019PKFHongKongLimited|AllRightsReservedPKFHongKongLimitedisamemberfirmofthePKFInternationalLimitedfamilyoflegallyindependentfirmsanddoesnotacceptanyresponsibilityorliabilityfortheactionsorinactionsofanyindividualmemberorcorrespondentfirmorfirms.
JeffreyLauTaxManagerjeffreylau@pkf-hk.
comHenryFungTaxPartnerhenryfung@pkf-hk.
comlinkedin.
com/company/pkf-hong-kong/https://www.
facebook.
com/PKFhkIMPORTANTNOTE:Theinformationcontainedinthisdocumentisonlyforgeneralinformationandisnotintendedtoaddressthecircumstancesofanyparticularentitiesorindividuals.
Accordingly,thisdocumentdoesnotconstituteaccounting,tax,legal,investment,consulting,orotherprofessionaladviceorservices.
Noactionshouldbetakensolelyonthebasisofthecontentsofthisdocumentwhichonlycontainabriefoutlineoftherelevantlaws.
Beforetakinganyaction,pleaseensurethatyouobtainadvicespecifictoyourcircumstancesfromyourusualPKFtaxpartnersorothertaxadvisersorliaisewiththerelevanttaxauthorities.
Weacceptnoresponsibilityorliabilitytoanypersonschoosingtotakeactionorimplementbusinessplansoractivitiessolelyorpartiallybasedonthisdocument.
PKFHongKongLimited26/F,CiticorpCentre,18WhitfieldRoad,CausewayBay,HongKongPKFconsistsofover400offices,operatingin150countriesacrossfiveregions.
Wespecialiseinprovidinghighqualityaudit,accounting,tax,andbusinessadvisorysolutionstointernationalanddomesticorganisationsinallourmarkets.
PKFTaxandBusinessAdvisoryprovidescomprehensivetaxandbusinessadvisoryservicesinrespectoftheInternational,HongKongandChinataxmatters.
OurprofessionalteamatPKFHongKongisexperiencedinprovidingcross-borderindividualincometaxadviceinvolvingHongKongandChina.
Ifyourequireassistanceinthisregard,pleasefeelfreetocontactus.
Contactus:FollowusonWeChatScantheQRcodeandgetthelatestPKFHongTel:+85228063822Email:enquiry@pkf-hk.
comWebsite:www.
pkf-hk.
com
- electronicwww相关文档
- 发行人www.e12.com.cn
- 发行人www.e12.com.cn
- 意见书www.e12.com.cn
- http://www.zhnet.com.cn
- 转换器www
- www.e12.com.cn上海高中除了四大名校,接下来哪所高中最好?顺便讲下它的各方面情况
10gbiz($2.36/月),香港/洛杉矶CN2 GIA线路VPS,香港/日本独立服务器
10gbiz发布了9月优惠方案,针对VPS、独立服务器、站群服务器、高防服务器等均提供了一系列优惠方面,其中香港/洛杉矶CN2 GIA线路VPS主机4折优惠继续,优惠后最低每月仅2.36美元起;日本/香港独立服务器提供特价款首月1.5折27.43美元起;站群/G口服务器首月半价,高防服务器永久8.5折等。这是一家成立于2020年的主机商,提供包括独立服务器租用和VPS主机等产品,数据中心包括美国洛...
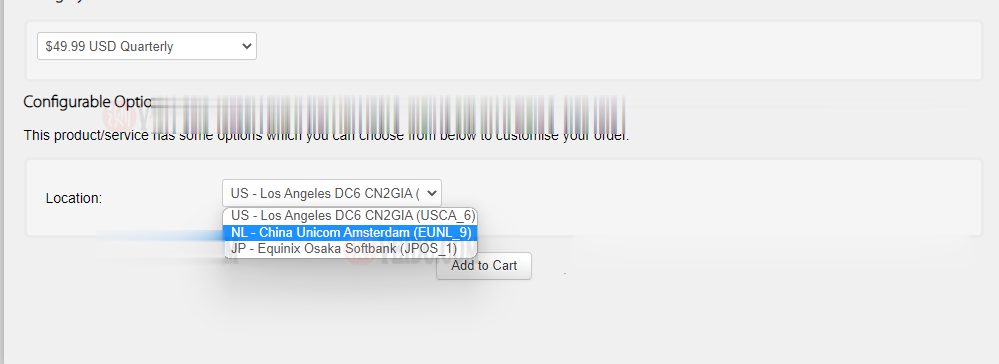
搬瓦工:新增荷兰机房 EUNL_9 测评,联通 AS10099/AS9929 高端优化路线/速度 延迟 路由 丢包测试
搬瓦工最近上线了一个新的荷兰机房,荷兰 EUNL_9 机房,这个 9 的编号感觉也挺随性的,之前的荷兰机房编号是 EUNL_3。这次荷兰新机房 EUNL_9 采用联通 AS9929 高端路线,三网都接入了 AS9929,对于联通用户来说是个好消息,又多了一个选择。对于其他用户可能还是 CN2 GIA 机房更合适一些。其实对于联通用户,这个荷兰机房也是比较远的,相比之下日本软银 JPOS_1 机房可...
Sharktech$129/月,1Gbps不限流量,E5-2678v3(24核48线程)
Sharktech最近洛杉矶和丹佛低价配置大部分都无货了,只有荷兰机房还有少量库存,商家又提供了两款洛杉矶特价独立服务器,价格不错,CPU/内存/硬盘都是高配,1-10Gbps带宽不限流量最低129美元/月起。鲨鱼机房(Sharktech)我们也叫它SK机房,是一家成立于2003年的老牌国外主机商,提供的产品包括独立服务器租用、VPS主机等,自营机房在美国洛杉矶、丹佛、芝加哥和荷兰阿姆斯特丹等,主...
www.e12.com.cn为你推荐
-
百度关键词价格查询百度竞价关键词价格查询,帮忙查几个词儿点击一次多少钱,thanks月神谭求古典武侠类的变身小说~!同ip域名不同的几个ip怎样和同一个域名对应上seo优化工具SEO优化要用到什么软件?sss17.comwww.com17com.com是什么啊?www.gegeshe.com《我的电台fm》 she网址是多少?javbibinobibi的中文意思是?partnersonline国内有哪些知名的ACCA培训机构www.ijinshan.com在电脑看港台电视台那个网站最好而又不用钱速度又快www.175qq.com最炫的qq分组